Grow Without Eating Your Own Cash
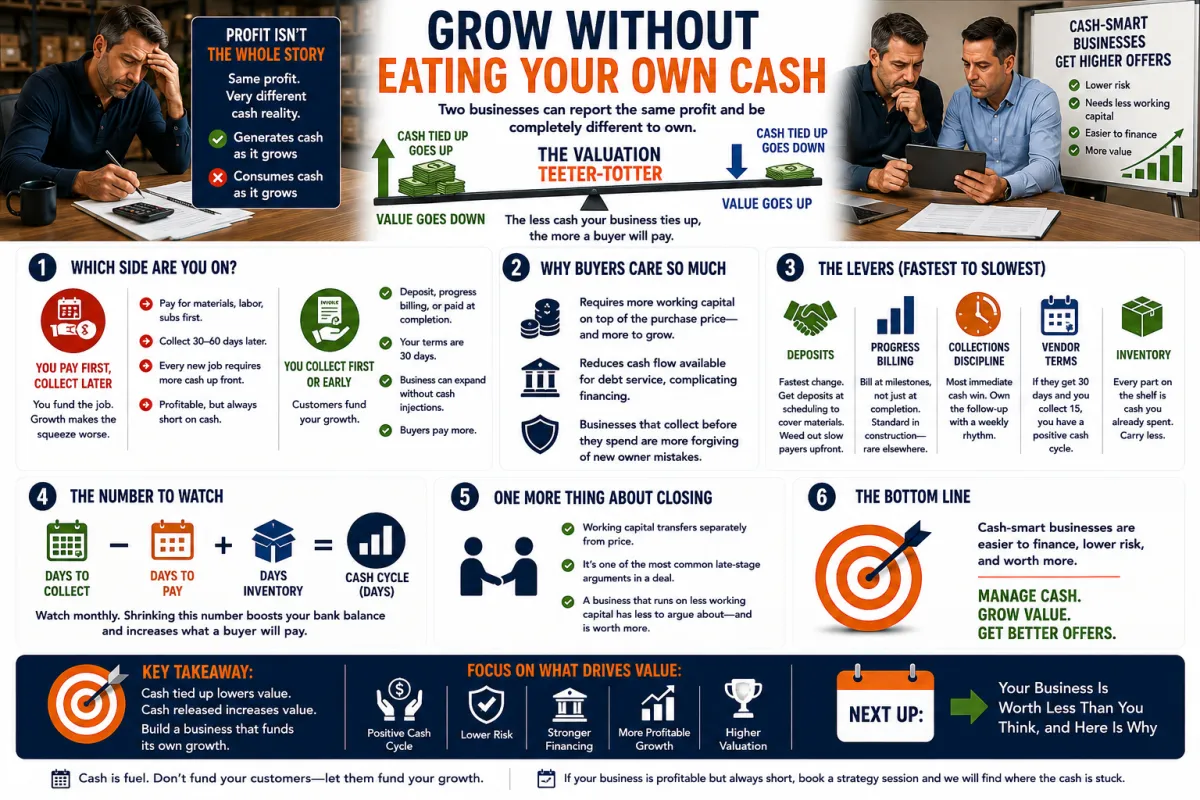
Two businesses can report the same profit and be completely different to own. One of them generates cash as it grows. The other consumes cash as it grows, and the faster it grows the more it consumes.
That difference is what the Valuation Teeter-Totter measures, and the name captures it well. As the cash the business ties up goes up, the value a buyer places on it goes down.
Which side are you on?
There is a quick way to tell. Think about a job from start to finish. When do you pay for materials, labor, and subcontractors? When does the customer's money actually arrive in your account?
If you pay first and collect thirty or sixty days later, you are funding your customers' projects out of your own account. Every additional job you take on requires more cash before it returns any. Growth makes the squeeze worse, which is why profitable businesses can still be short every month.
If you collect a deposit up front, bill progressively, or get paid at completion while your own terms run thirty days, then your customers are funding your growth. That business can expand without an injection of capital, and buyers pay more for it.
Why buyers care so much
Because a cash hungry business changes what the buyer has to bring to the table. On top of the purchase price, they need working capital to run it, and more working capital if they intend to grow it.
That extra requirement comes out of your price. It also complicates financing, because the lender is looking at whether cash flow covers debt service, and a business that consumes cash to grow has less margin for the payment.
There is a second reason, less discussed. A business that collects before it spends is more forgiving of mistakes. A new owner will make some. The cash position determines whether those mistakes are expensive lessons or existential ones.
The levers, roughly in order of how fast they work
Deposits. The single fastest change most service businesses can make. A deposit at scheduling, sized to cover materials, moves you from financing the job to being financed for it. Owners resist because they fear losing work, and then find that customers who will not put money down were often the ones who paid slowly anyway.
Progress billing. On anything running more than a couple of weeks, bill at milestones instead of at completion. This is standard in construction and strangely rare in adjacent trades.
Collections discipline. Not glamorous, and usually the largest immediate win. Most businesses have receivables aging well past terms because nobody owns the follow-up. Assigning it to a specific person with a specific weekly rhythm frequently pulls in more cash than a month of new sales.
Vendor terms. If your suppliers give thirty days and your customers pay in fifteen, you have a positive cash cycle. Ask for terms. Long standing accounts often get them for the asking, and nobody asks.
Inventory. Every part sitting on a shelf is cash you already spent. Most shops carry more than they need because it feels safer, and the carrying cost is invisible until you measure it.
The number to watch
Track the gap in days between when cash leaves and when it returns. You do not need sophisticated tools. Average days to collect, minus average days you take to pay, plus days inventory sits, gets you close enough to manage it.
Watch that number monthly. Shrinking it is one of the few improvements that shows up immediately in your bank balance and simultaneously raises what a buyer will pay.
One more thing about closing
How much working capital transfers with the business is negotiated separately from price, and it is one of the most common late stage arguments in a deal. A business that runs on less working capital has less to argue about.
If your business is profitable but always short, book a complementary strategy session HERE and I'll help you correct it!