Seller's Discretionary Earnings, Explained Simply
A seller hands me a tax return showing ninety thousand dollars of net income and tells me the business really makes about six hundred thousand. He is not lying. He is also not going to get paid six hundred thousand unless he can show his work.
Seller's Discretionary Earnings is the bridge between those two numbers. It is an attempt to answer one question: how much money does this business actually produce for one working owner, before that owner decides what to do with it?
Almost every valuation conversation in the $3M to $10M range starts with SDE, and almost every argument in diligence is about a line inside it. It is worth understanding before you are in the middle of one.
How the number gets built
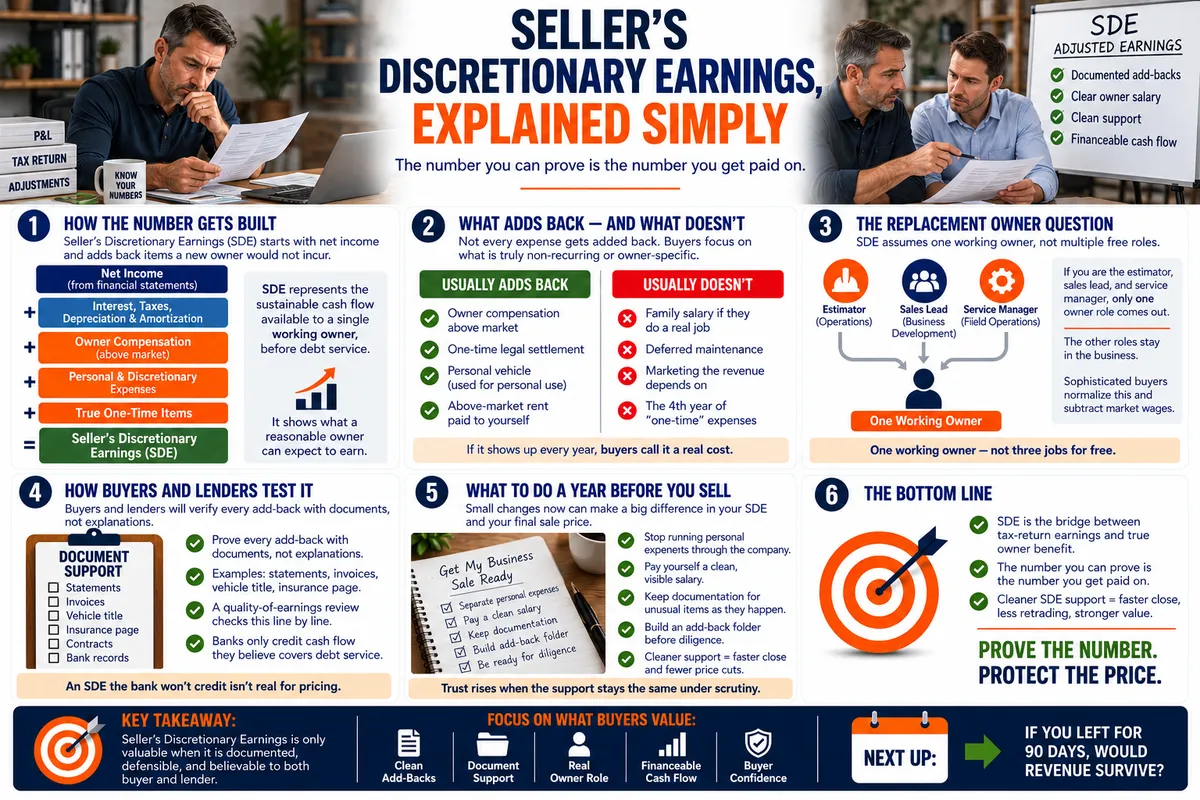
You start at the bottom of the tax return and work up. Net income, then add back interest, taxes, depreciation, and amortization, which gets you to EBITDA. Then add back the owner's compensation and benefits, plus personal or discretionary expenses that ran through the company, plus genuine one-time items.
For a trades business that often includes the owner's salary and payroll taxes, the health insurance for the owner's family, the truck the owner drives, a phone plan with four family lines on it, and the trip to the manufacturer conference in Scottsdale that happened to fall over a long weekend.
Each of those is legitimate if it is real, documented, and would genuinely not exist under a new owner. That last clause is where most add-backs die.
What adds back and what only looks like it does
Clean add-backs share three traits: documentable, non-recurring or clearly personal, and not required to produce next year's revenue.
Things that usually add back include owner compensation above market, one-time legal settlements, the personal vehicle, and rent paid to yourself above market rate.
Things that usually do not, no matter how the seller feels about them, include the salary of a family member who actually does a job someone would have to be hired to do, deferred maintenance on trucks and equipment, marketing you cut last year that revenue depends on, and the fourth consecutive year of one-time expenses.
The last one is worth repeating. If an expense has appeared three years running, a buyer stops calling it unusual and starts calling it a cost of doing business.
The replacement owner question
Here is the piece sellers miss most often. SDE assumes one working owner. If you are the estimator, the sales lead, and the service manager, all three of those jobs stay in the business after you leave, and only one of them comes out of SDE as your compensation.
A sophisticated buyer will normalize this. They will price a general manager at market for your area, subtract it, and run the deal on what is left. If you are working eighty hours a week doing three people's jobs, your SDE is overstated by roughly two salaries, and the buyer will find it in the first serious conversation.
How buyers and lenders test the number
Expect to prove every add-back with a document, not an explanation. Credit card statements, invoices, the vehicle title, the insurance declaration page. A quality-of-earnings review, which is common once deals get larger, exists to do exactly this line by line.
Lenders apply their own filter. A bank financing an acquisition cares whether the cash flow covers debt service with room to spare, and it will reject add-backs a buyer might have accepted. The practical effect is that an SDE number the bank will not credit does not really exist for pricing purposes. SBA and lender treatment of add-backs varies by institution and changes over time, so confirm specifics with your own lender, accountant, and attorney. This is not legal or tax advice.
What to do about it a year before you sell
The cheapest fix is to stop creating the problem. Run personal expenses through personal accounts. Pay yourself a clean, visible salary. Keep documentation for anything unusual in a folder as it happens rather than reconstructing it under diligence pressure.
Sellers who do this get a faster close and fewer price reductions, because nothing erodes buyer trust like an add-back schedule that shrinks every time someone asks a question. The number you can prove is the number you get paid on.
Once SDE is settled, the next argument is about the multiple applied to it, and that is where the difference between a listed price and a financeable value shows up.
If you want to know what your real, defensible SDE looks like before a buyer builds it for you, book a strategy session and we will work through your last three years together.